Wednesday, June 10, 2009
A Textbook Example of the Free-Rider Problem
My colleague (an economist, by the way) didn't recognize that even if American students care about the welfare of foreigners, they still have a strong in incentive to buy international editions. This is a "textbook" case of the free-rider problem. A single student who refrains from buying the international edition bears the entire cost of paying a higher price. She does not, however, receive the benefits of knowing foreign students can buy affordable textbooks, since she recognizes other American students won't similarly refrain. Perceiving that others will buy the international edition, each student has an incentive to buy the cheaper textbook.
This free-rider problem could be overcome through the legal system. But I don't know (a) if buying (or selling) international editions in America is illegal, or (b) if any government agency enforces these laws if they do exist. My students don't know the answer either, so if such laws exist, they're obviously not an effective deterrent.
We Need Accurate Predictions!
The Chicago school is deductive in its results; virtually all its theories rely on the assumption that consumers and producers are rational. To Chicago-school economists rationality means that consumers use all available information to make choices that maximize subjective well-being. While Chicago-school economists do not suppose that people are all knowing, they do assume that people are generally correct in their beliefs and assumptions about the future. Critics of the Chicago school typically overstate the assumptions of its adherents, claiming that such economists envision people as being omniscient.
Milton Friedman responded to some of these criticisms in an essay, "The Methodology of Positive Economics." According to Friedman, the way to test the validity of models is by analyzing the accuracy of their predictions, not by the accuracy of their assumptions. Thus, although people may not be as rational as the Chicago school supposes, Chicago-school theories are valid if they make accurate predictions. The reason that the Chicago school has been so successful is that its models have been confirmed by a wealth of data.
Furthermore, according to Friedman – and the principle’s embodied by Ockham’s razor – if multiple models make equally accurate predictions, the best model is the simplest. These views are not exclusive to economists: the great theoretical physicists Stephen Hawking makes similar claims in A Brief History of Time.
Anyway, back to Delong –
The review is based on an analogy comparing (a) Chicago-school adherents to 17th Century Jesuits and (b) enlightened economists (presumably behavioralists who acknowledge irrationality) to Copernicans. Jesuits believed that the sun revolved around the earth. Copernicus’s model claimed otherwise. Despite mounting evidence, the Jesuits clung to their beliefs by developing increasingly complicated models. Nonetheless, the Jesuit models couldn't predict planetary movements as successfully as Copernicus's simple but elegant model.
The Jesuit/Copernican analogy is the most ill-advised part of the review (other than perhaps DeLong’s failure to define rationality, as Posner points out in a response). The reason is that in economics, it is the behavioralists who are proposing increasingly complicated models and assumptions. Furthermore, with a few exceptions the behavioralist models are not able to predict behavior as effectively and accurately as rationality-based models. The assumptions of behavioralist models are often vague, ad hoc, and inconstant from model to model. Behavioral predictions are generally non-quantifiable and difficult to implement in non-laboratory settings. Until behavioral economics can make predictions that are more accurate than neoclassical predictions, its claims of irrationality will be meaningless.
This post may seem surprising, given the blog subtitle. I indeed identify as a behavioral economist - or rather as an economist who dabbles in behavioral research. In my view behavioralism can offer useful insights into economic decision-making. Nevertheless, behavioral economics will be little more than an interesting footnote until it can consistently make accurate predictions.
In a later post I'll identify some behavioral predictions that are more accurate than neoclassical predictions.
Tuesday, June 9, 2009
"His analysis, however, slices far from the fairway"
In his 12-page opinion, Judge Dixon used golfing metaphors to explain his legal reasoning at least 10 time (there may be more examples that I missed). At one point the judge quotes a line from Caddyshack. Anyway, I included all of the references for your reading pleasure. Good stuff:
Plaintiff tees up his case . . . (p. 2). His analysis, however, slices far from the fairway (p. 5). This attempt to change arguments . . . is like trying to change clubs after hitting the golf ball–Plaintiff is stuck with the club (in this case the argument) that he first picked (p. 6). Therefore, Plaintiff’s reliance on four student policy manuals as evidence of a contract is a swing and a miss (p. 6). Ross serves as a putter, however, where Plaintiff needs a sand wedge to get out of the hazard (p. 7). Plaintiff attempts to take a mulligan with this argument; however, this shot also lands in the drink (p. 9). Plaintiff also shanks this claim (p. 10). Plaintiff’s promissory estoppel claim . . . brings to mind Carl Spackler’s analysis from the movie CADDYSHACK (Orion Pictures 1980): “He’s on his final hole. He’s about 455 yards away, he’s gonna hit about a 2 iron, I think” (p. 10). Plaintiff tries to get around the slow play of his promissory estoppel claim . . . (p. 11). Plaintiff’s fifth and final claim . . . can be disposed of with a hole-in-one sentence: no valid contract means no declaratory judgment (p. 11).
Sunday, June 7, 2009
Are We Running Out of Oil?
Here's my essay (slightly modified):
Even economists make mistakes. William Jevons’ book The Coal Question provides a prime example. Jevons was a brilliant nineteenth century intellectual. He was not, however, infallible. In his treatise, Jevons predicted the collapse of England’s economy due to impending coal shortages: “[the current] rate of growth will before long render our consumption of coal comparable with the total supply...we shall meet that vague but inevitable boundary that will stop our progress.” W. Stanley Jevons, The Coal Question: An Inquiry Concerning the Progress of The Nation, and the Probable Exhaustion of Our Coal-Mines 200 (3rd ed. 1906) (1865).
Jevons disregarded the underlying economic principles he professed. If less coal is available, its price increases. This leads to three effects. First, because each lump of coal costs more, people are conservative in their coal use. Second, coal’s higher price serves as an impetus for exploration; entrepreneurs seek new deposits. Finally, lucrative markets for substitutes emerge.
What happened in Great Britain? Was Jevons right? Clearly, coal has not vanished. Furthermore, the economy has increasingly relied on another energy source: oil. Adam Smith’s invisible hand works.
Modern forecasters are raising similar concerns about the coming oil crisis. We have reached “peak oil,” and our economy must soon change how it meets its energy needs. Current naysayers present arguments that are eerily similar to Jevons’: “[as] consumption begins to exceed production by even a small amount,” there will be “a global recession.” Such alarmists likewise fail to consider fundamental truths. Though society must eventually shift to other energy sources, the conversion will be neither catastrophic nor expeditious. Markets will facilitate the change through gradual adjustments in price, conservation techniques, and alternative energy options. There is no impending oil crisis.
The Purpose of Behavioral Economics
The project of behavioral law and economics, as we see it, is to take the core insights and successes of economics and build upon them by making more realistic assumptions about human behavior. We wish to retain the power of the economist’s approach to social science while offering a better description of the behavior of the agents in society and the economy. Behavioral law and economics, in short, offers the potential to be law and economics with a higher “R2”—that is, greater power to explain the observed data. We will try to highlight some of that potential (and suggest cases where it has been realized) in this article. (p. 1487)
Proposing more realistic economic assumptions is a pointless exercise unless the assumptions increase the ability of models to predict. Thus, the proof of behavioral economics is, as they say, in the pudding.
Did the Free Market Cause the Current Crisis? - Part II
Factor #2: The Government - "Ownership Society"
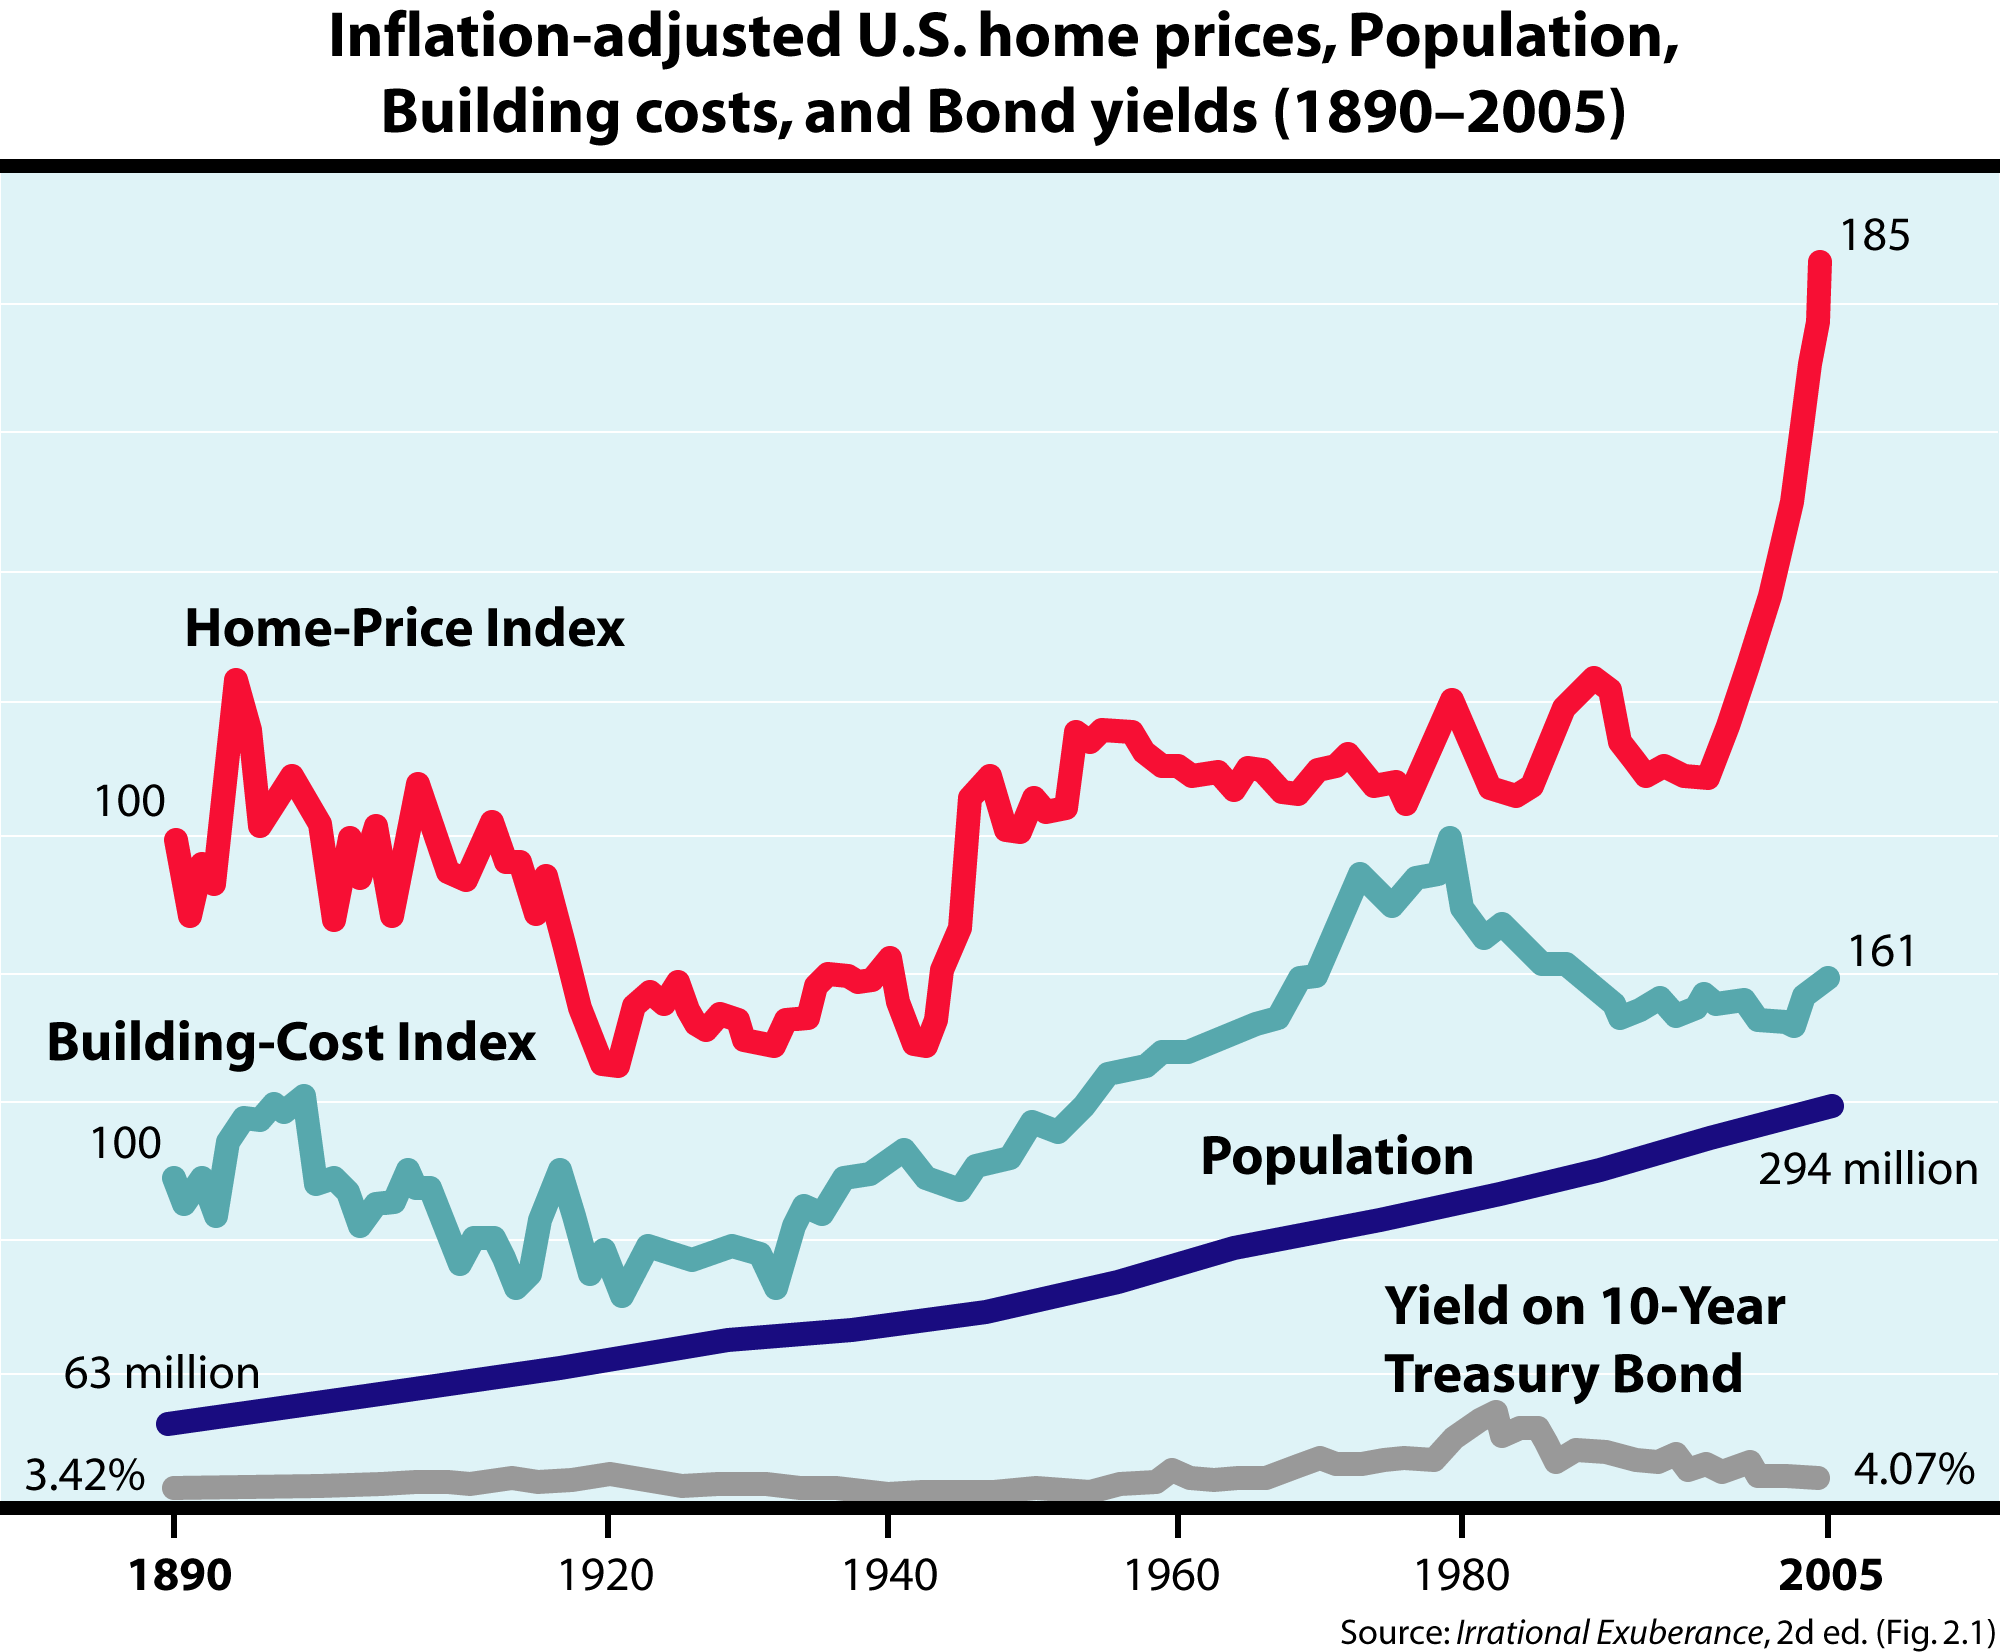
In the late 1990s people began to believe that homes were always safe investments. One reason is that home prices had steadily risen during previous decades, and people simply believed that the increase would continue (behavioral economists call this "status quo" bias). Another reason is that income and population were rising in the 1990s, so more people could afford homes.
As people increasingly viewed homes as safe investments, demand and therefore prices rose. Soon many people were unable to afford 20 percent down payments. People began arguing that low income Americans, especially minorities, were unfairly denied the American dream. Beginning with the Clinton administration, the government began pushing Fannie Mae and Freddie Mac to offer loans to low-income Americans - under the implicit guarantee that the government wouldn't allow these institutions to fail. (This implicit guarantee explains why these institutions could borrow at low rates, despite the fact that they back so many risky loans). The government encouraged lenders to offer loans to people who would be unlikely to afford payments. Unfortunately, the Bush administration continued Clinton's inauspicious policies. President Bush hoped to achieve an “ownership society.” Furthermore, the federal government - and many state governments - began offering strong tax incentives to home buyers.
Still, it's possible to argue that it's a good idea for the government to encourage homeownership because of the positive externality effect: homeowners take better care of their properties than renters do, which increases neighborhood property values. Homeownership may also reduce crime - at least according to Giuliani's "broken window" theory. Nevertheless, as the recent crisis suggests, the government went way too far in its encouragement of homeownership.
The perpetuation of the idea that homes were safe investments and the government's encouragement of homeownership were not independent events. Each fueled the other. These events, along with the Fed's lowering of interest rates and banking deregulation, led to the huge spike in real home prices.
Before claiming that free markets caused the current crisis, however, it’s important to recognize that two of the three culpable events have nothing to do with free markets and everything to with government intervention.
Privatizing Social Security is a Good Idea - Still
In Richard Posner's book A Failure of Captilism (a great book I'll blog more about in the future), Judge Posner listed lessons this crisis has taught us. One thing he mentioned is that privatizing Social Security would have been a bad idea. He never explained his rationale (perhaps he thought it was self-evident?), and, for the reasons listed below, I don't agree with his claim.
First, it would initially seem that the people who would have been hurt the most by privatization are those (a) who had heavily invested their money in the stock market, and (b) who are close to retirement. But privatized accounts would likely work much like 401(k)'s. People could choose to invest in stocks, bonds, or some preset mix. As people approached retirement, most would shift their money to bonds, where funds have largely been sheltered. Most soon-to-be retirees wouldn't have been significantly affected by the crisis.
Secondly, it’s true that crisis would have harmed anyone who had invested in stocks. Still, I expect the return on stocks over the next decade or two to exceed the current return on Social Security contributions (which is close to two percent). Even those who would have been significantly hurt in the short-run would be better off by investing in stocks than by "investing" in Social Security - as long as they aren't looking to retire in the next couple of years.
Finally, privatizing social security would have encouraged higher savings rates, so people would have saved more in the early 2000s. Thus, when the crisis hit, people could have drawn on their savings, mitigating the sharp decline in consumption. Much of the savings, of course, would have gone to untouchable 401(k)-type accounts, but Congress could have simply passed a law allowing people to withdraw early without the standard penalty. Because the value of stocks will likely grow faster than two percent, people who withdrew early would still have money for retirement.